All Categories
Featured


Part D Enrollment Strategies for the 2026 Season
Table of Contents
You are paying for permanence and ensured cash worth, not simply a survivor benefit. Larger whole life policies scale up roughly in percentage to the face quantity. If your objective is pure income replacement, term life provides much more protection per dollar; if your objective is ensured long-term protection no matter how long you live, entire life is developed for that.
Below are normal term life rates for seniors a $250,000 10-year term policy (male, non-smoker): AgeMonthly PremiumAnnual Cost60$70$84065$120$1,44070$210$2,52075$380$4,560 Most providers top term length as you age a 20-year term is commonly available at 60 but seldom at 70. Match the term to a specific requirement (a remaining home mortgage, a partner's earnings space).
A single regulated condition (high blood pressure, cholesterol) has a bigger dollar impact at 65 than at 35. A specialist broker assists you discover the provider that treats your health most favorably. For a deeper breakdown, see our dedicated guides for life insurance over 50 and life insurance over 60. This is the most inexpensive time to purchase, even if your protection needs are modest.
HMO vs PPO Health Insurance Plans
Lock in the most affordable rate possible for the longest duration. You can always include more protection later. Peak purchasing time. Many people start families, buy homes, and hit their stride in their careers. SituationRecommended CoverageMarried, kids, mortgage$750K-$1.5 MSingle parent$500K-$1MHigh earner ($150K+)$1.5 M-$3MPersonal + essential person protection 20-year level term if your kids are young.
SituationRecommended CoverageKids heading to college in 5-10 years$500K-$1M (match to remaining years)Big home mortgage remainingCoverage matching balanceApproaching peak making years10-15x earnings 15 or 20-year level term. If you currently have a 30-year term from your 30s, you may have enough.
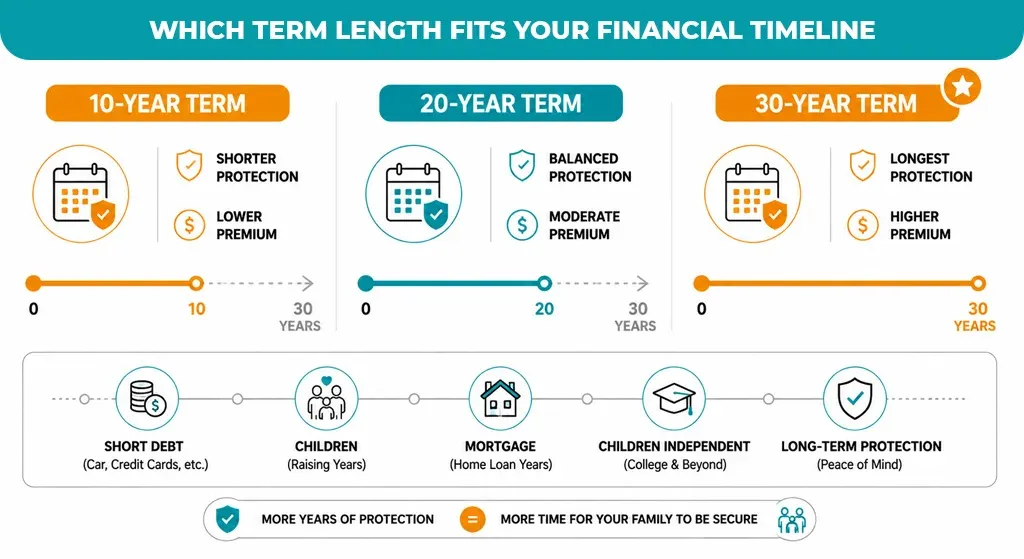
Kids might be independent, mortgage is shrinking, and retirement cost savings are growing.
Securing Affordable Family Health Insurance in 2026
SituationRecommended CoverageFinal expenditures only$15K-$25K whole life or burial insurancePartner income protection$100K-$250K termLegacy/ inheritanceWhole life based upon desired bequestEstate tax planningConsult estate lawyer Last cost whole life for many. 10-year term for particular short-term requirements like a staying home mortgage. Here is the real cost of procrastination: Purchase AgeMonthlyTotal Over 20 YearsExtra Expense vs.
Which assumes you remain healthy. If you develop a health condition while waiting, the boost is even bigger. The math is basic: buy now, pay less. Get a complimentary life insurance quote and see precisely what coverage costs at your age. What is the very best age to buy life insurance? The very best age is as young as possible.
A 25-year-old pays roughly half what a 35-year-old pays for the same coverage. Buying in your 20s locks in the lowest rate for the longest duration. Just how much does life insurance coverage boost by age? Rates boost about 8-10% per year in your 20s-30s, 10-15% annually in your 40s, and 15-20% per year in your 50s-60s.
Insurance in Camarillo CA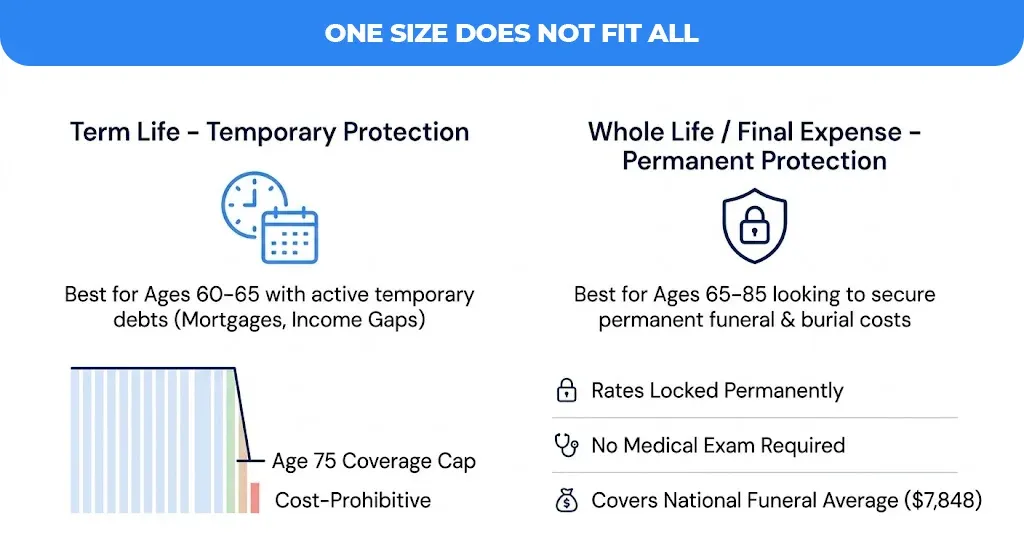
Top Medicare Supplement Coverage in 2026
Is it far too late to purchase life insurance coverage at 60? No. While rates are higher, a healthy 60-year-old can get $250K in 10-year term protection for about $78-100/ month. Last cost policies are a lot more cost effective. Protection is available at any age. What are entire life insurance coverage rates by age? Whole life is several times more costly than term because the protection is long-term and builds cash value.
Ladies pay roughly 10-20% less. Larger entire life policies scale up from there. See the entire life chart below. What are typical life insurance rates for seniors? For a healthy senior, a $250,000 10-year term policy (male, non-smoker) costs approximately $70/month at age 60, $120/month at age 65, and $210/month at age 70.
Rates increase steeply with age, so using sooner rather than later matters most in this bracket. Compare rates from leading life insurance carriers. In this post, we'll break down the different aspects that influence life insurance expenses, how much you can expect to pay, and pointers for getting the finest rates.
The buying a 20-year term policy for $250,000 in protection. for the very same coverage. looking While the. Term Life insurance coverage is frequently referred to by other names, such as "instant life insurance" or "no test life insurance." These terms explain various kinds of term life insurance coverage policies. Life insurance coverage tends to be more pricey than special needs insurance because it provides a death benefit to recipients, which can be a substantial amount of money.

Latest Posts
Understanding 2026 Medicare Advantage Enrollment

Navigating the 2026 Medicare Part D Enrollment Period
Part D Enrollment Strategies for the 2026 Season