All Categories
Featured

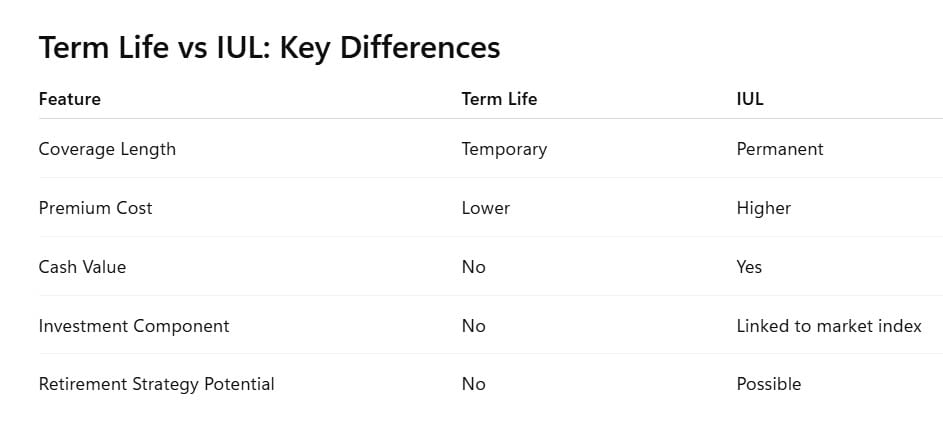
Protecting Financial Security with Term Life Insurance
However, these exact same Indexed Universal Life items will significantly underperform if they're light funded and/or their performance does not have. That suggests that the internal charge load baked into the item is greater than it needs to be, and heavily depending on performance to outrun the costs. These improperly designed products that get sold to the unsuspecting masses are the factor you typically hear IUL is a continuous combination of debits and credits, so it's sensible to know what both sides of the ledger appear like.
It's quite basic nowadays for most IUL policies to have some sort of participating loan choice, where your cash worth still has market exposure even while obtaining against it for emergency situations or chances. Also, it's wise to consider the spread between whatever the loan rate is and the cap so you know what sort of positive arbitrage you can anticipate in bullish years.
Having an integrated mechanism to catch this possible arbitrage will be critical in choosing the best-performing IUL policy. There are IUL calculators to help you identify if you can anticipate long-term favorable arbitrage on your money value over various timeframes during bull and bearish market. Very same age, very same rating, Same premiumDifferent companies, Different styles, Drastically various money valuesSee how your policy accumulates.
For these factors,, who is staying abreast of this rapidly altering market and can signal you to the most recent news and chances. It's not unexpected that Penn Mutual ranks the greatest of the very best IUL business in regards to warranties since they likewise offer the best-performing Whole Life policy, a product understood for its guarantees.
Several of Penn Mutual's indexed accounts come with an ensured 1% floor, which indicates that even in down market years, you earn interest to offset the continuous cost of the death advantage. In spite of this 1% floor, Penn Mutual still provides competitive caps on its S&P 500 methods. Unlike the other best IUL business on this list, Penn Mutual does NOT offer Volatility Control Index techniques.
Prescription Drug Coverage Guide for 2026
(In case you missed it above, VCIs are algorithmic market timing techniques handled by well-known financial investment banks with high internal expenses and an absence of openness). Competitive Caps on the S&P 500 (sometimes with a 1% flooring rather of 0%)The ability to raise your S&P 500 cap (for an extra cost or spread of around 3%)Uncapped S&P 500 crediting techniques for optimum growthWith Penn Mutual's contractually locked 6% policy loan rate for the life of its IUL policy, you can keep your money worth operating in the S&P 500 Index even while borrowing versus it for emergency situations or outdoors investment chances.
Allianz occurs to be the only on the list and a foreign stock business at that. It's legitimate to worry that a German parent company might not have obligation to American policyholders if financial times get difficult, but others like the truth a foreign stock business has differed sources of incomes in varied insurance markets.
This permits them to provide their "rate lock feature," where IUL policy owners can freeze whatever gains they have at any point throughout the year. It's worth noting that you can just do this with their different volatility control indexes (VCIs) and not the pure S&P techniques. In fact, Allianz likewise has different fee options that enable you to increase your exposure to their indexed options.
Allianz is among the very best IUL companies because of their diverse set of IUL investment optionsIt's worth noting that I've been an Allianz insurance policy holder given that 2014, and I can testify to the truth that my IUL caps and participation rates aren't as competitive as what they've consistently used on whatever their newest item is.
Senior Insurance Guide
Therefore, it's crucial to stress-test how Allianz's IUL policy holds up at lower crediting rates compared to the other top Indexed Universal Life business. A wide assortment of exotic indexes to pick fromRate-lock feature when using the volatility control indexesAbility to be more aggressive with a 40% multiplier (for a 1% fee)Locked 5% loan rate to obtain versus any of the indexed accountsTheir "Index Lock" only deals with Volatility Control Indexes, not the pure S&P strategies.
Ok, there, I did it. You understand you were believing it too. But that actually is why Nationwide is one of the top IUL business. Their size, rating, and total financial strength are unmatched. Not only that, but they are a real shared company, implying they have no outside shareholders nor a holding business to siphon revenues to.

Latest Posts
Protecting Financial Security with Term Life Insurance
Evaluating 2026 Medicare Advantage Plans in Highland
The Difference Between Universal and Indexed Universal Life Policies